The Payday Rollover Trap Fits on One Calendar
The most important payday-loan calculation is not annual percentage rate. It is whether the borrower can repay on the exact due date and still cover the next rent, food, transport, utilities, and medicine.
A rollover trap is visible before the loan is signed if the dates are written down honestly.
Build the two-pay-cycle view
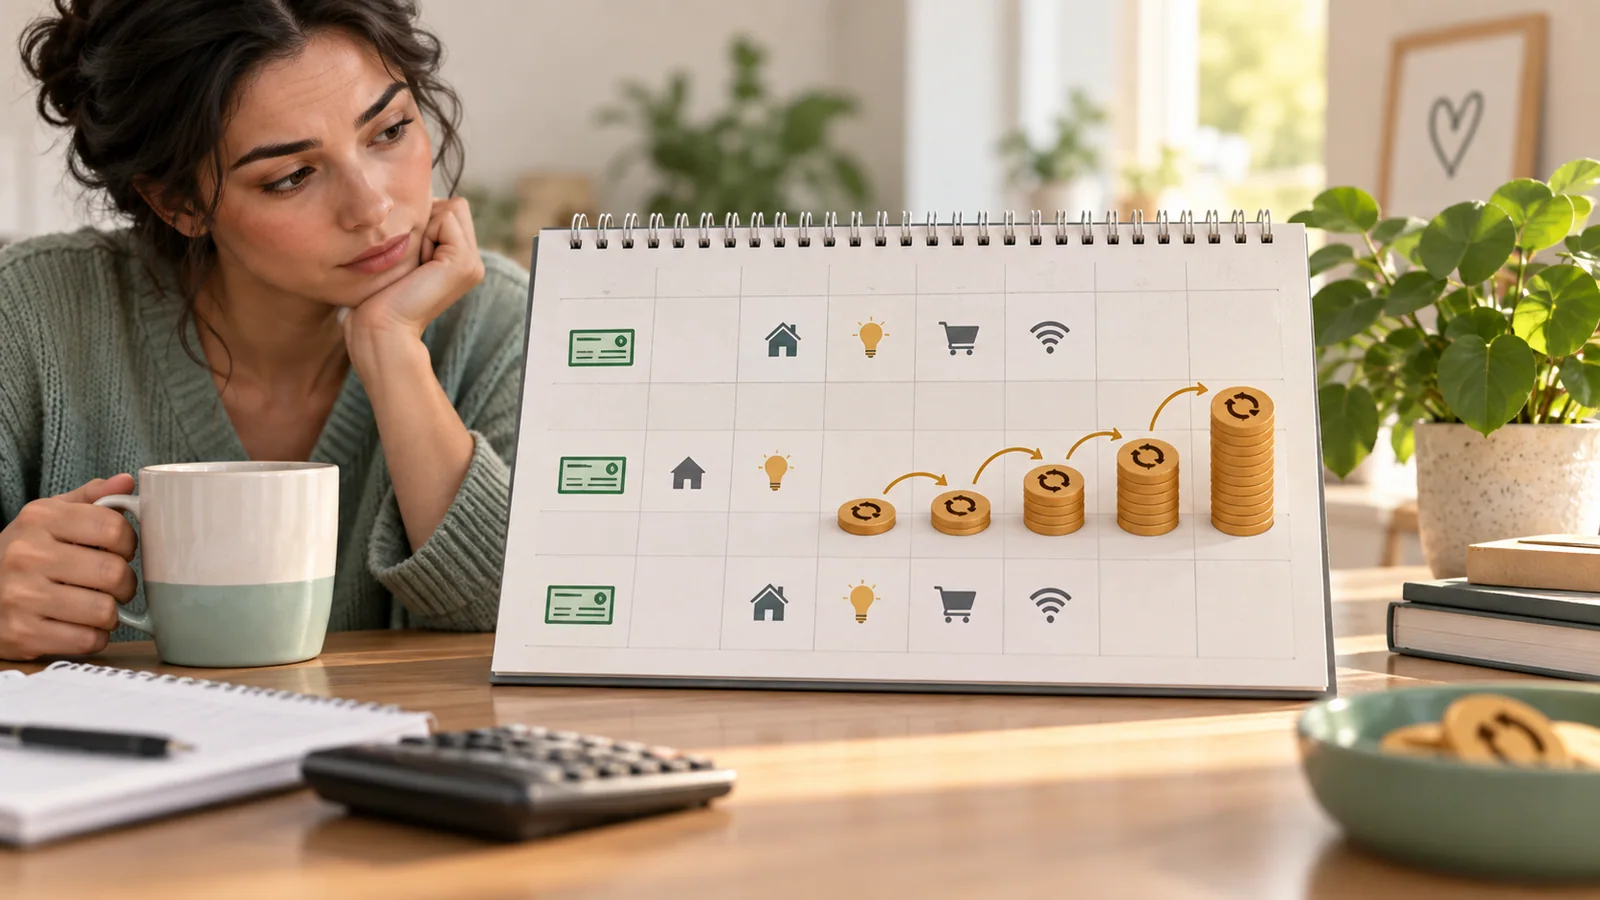
Create a simple calendar covering today through two paydays after the loan comes due. Enter only money that is reasonably certain to arrive. Then place every essential bill on its real date.
Add the loan as one full repayment: principal plus fee. Do not assume a rollover unless the contract permits it, and do not treat a rollover as free time. It normally adds cost while leaving principal unresolved.
| Date | Cash in | Essentials | Loan payment | Running balance |
|---|---|---|---|---|
| Payday | known income | bills due | full contractual amount | calculate |
| Following week | known income only | food, transport, utilities | any remaining debt | calculate |
If the balance goes below zero, the problem is not a future surprise. It is in the original structure.
Why APR still matters
APR helps compare costs across products with different terms. A fee that looks modest over 14 days can produce a very large annualized rate. But APR alone does not show whether rent is due three days after repayment. Use APR for comparison and the dated calendar for survivability.
The dangerous sentence
“I’ll figure it out next payday” is not a repayment source. Name the exact expense that will fall, income that will rise, or asset that will be sold. If nothing changes, the next payday carries the same household plus the loan fee.
Before borrowing, compare employer advances, negotiated bill dates, payment plans, credit-union small-dollar options, assistance programs, borrowing from someone trusted, or selling an item. Each has tradeoffs; the point is to compare the full dollar and relationship cost.
If repayment is already failing
Contact the lender before the due date and ask about any extended repayment plan required or offered under local rules. Review the ACH authorization and procedures for stopping future electronic payments without assuming that stopping a debit cancels the debt. Preserve communications.
Sources and limits
Options and rights vary by location and lender. This article is consumer education, not individual financial or legal advice.
Key takeaway
The rollover trap is a date problem before it becomes a debt problem. If the full repayment makes the next two pay cycles negative, find an alternative before the contract starts charging for hope.
payday rolloverdebt cyclecash flowloan fees